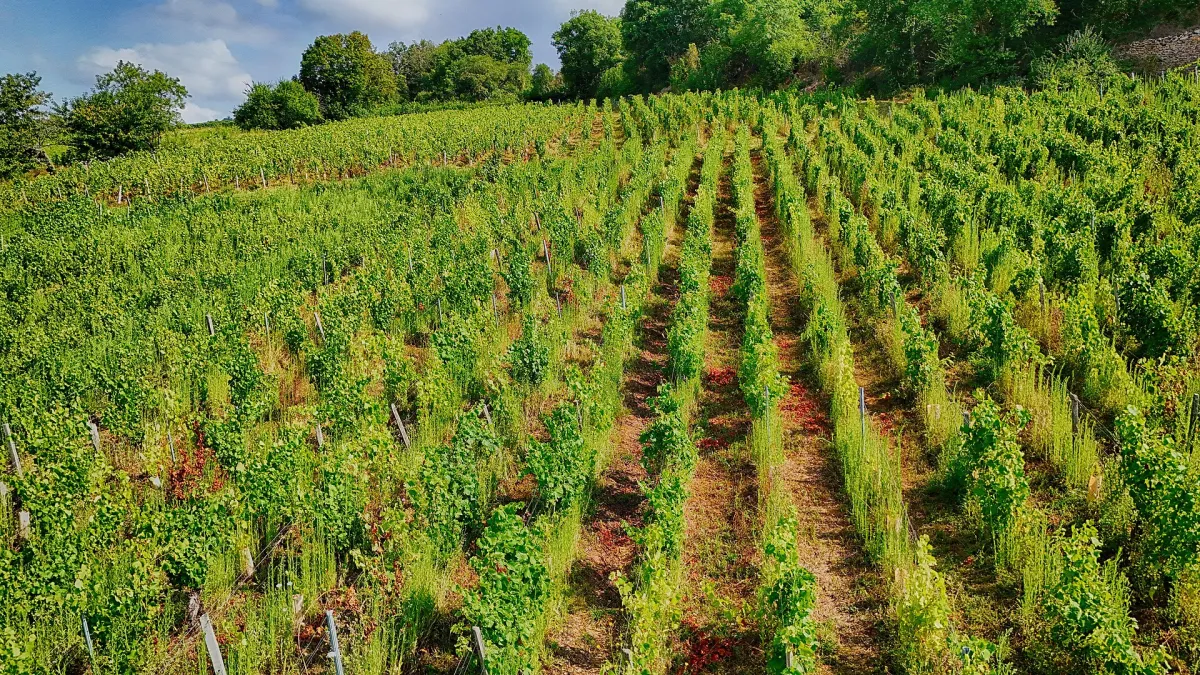
A leading Burgundy domaine may make a few thousand bottles of its top wine in a year — less than a day's production for a serious Bordeaux château. From that arithmetic everything else follows: the allocations, the merchants' waiting lists, the prices that look like misprints, and the fact that many who buy the wine never drink it, while most who drink it could never buy it now.
An index for a market that barely trades
Liv-ex, the London-based fine-wine exchange, publishes the indices everyone quotes — the Liv-ex 100, the broader 1000, and regional measures including a Burgundy index. They track the prices of the most traded wines among professional merchants, which makes them useful and narrow at once. The wines that make headlines — small-production Burgundy from cult domaines — barely trade, so the index describes their world only loosely.
Treat the indices as weather reports for a climate you can observe but not farm. They will tell you that fine wine corrected after its 2021–22 run, which it did, and that Bordeaux's share of trade has shrunk as Burgundy and Champagne grew, which it has. They cannot tell you what your case is worth on a given Tuesday.
The merchants behind those prices operate on spreads, not spreadsheets. The figure on a merchant's list is an offer, not a promise; when you sell, you meet a bid sitting meaningfully below it, and the gap widens precisely when everyone is selling at once. A case you might need to exit quickly is worth less to you than the sheet says, and a case you never need to sell is worth more. That asymmetry should decide the size of the position long before any view on vintages does.
Scarcity against thirst
Burgundy's bull case is consumption itself. Every bottle drunk reduces supply permanently, and the region's great reds and whites are drunk constantly — in Hong Kong more than most places, where the auction rooms and restaurant cellars have been deep for decades. The bear case is the same fact read the other way: your asset pays out only when someone else opens their wallet at a restaurant, and that appetite is cyclical.
Access runs through allocations. The domaines release to merchants they have known for decades; merchants release to clients who buy the unglamorous vintages too. The client who cherry-picks the great years stops receiving the email. Vintage variation adds a second axis — Burgundy delivers small, uneven harvests as a matter of course, and a hailed-out year raises prices while cutting volume. This is not a market that rewards leverage.
Provenance lives in a warehouse
The gap between a case in bond and a case in someone's flat can be the entire investment case. Professional bonded storage — in the UK, or in Hong Kong, which abolished wine duty in 2008 and built a storage industry on the back of it — keeps the wine cool, the duty suspended and the paperwork clean. Buyers pay for original wooden cases, good fill levels, unmarked labels and an ownership chain with no gaps.
Buy in bond, keep it in bond, and take delivery only of what you intend to drink. Insure at market value, and reconcile the warehouse's records with your own once in a while. The moment a case travels, it starts becoming furniture.
Open more than you sell
The healthiest cellar runs a surplus of pleasure: the cases you open should outnumber the cases you sell, by a comfortable margin. Wine bought as pure investment pays no dividend, charges you storage, and returns capital — if it returns it — in a market where the buyer trusts your storage more than your story. Wine bought to drink carries an option. If prices rise, you drank well below replacement cost; if they fall, you drank well anyway.
Practical housekeeping decides more outcomes than market timing. Keep the wine with an established bonded warehouse rather than in a merchant's own cellar where you can, refresh the insurance valuation as prices move, and maintain a plain record of what each case cost and when it moved. None of this is exciting. All of it is what separates a cellar from a pile of expensive glass when the time comes to sell, to claim, or to inherit.
As of late 2026, back vintages of serious Burgundy look saner than they have in years, after the correction that followed the post-pandemic spike. For drinkers with cold storage and patience, that is the whole opportunity. The investors will be back when the indices tell them it is safe — which is precisely when it will not be.