Every residential brochure above a certain price says the same word. Prime. It is the most abused adjective in property, stretched across new towers with forty identical neighbours, across resorts with a thousand identical villas, across anything with a concierge and a rendering of a lobby. In the decade when money was nearly free, the abuse did not matter much: rising prices forgave loose definitions. In a decade where money has a price again, definitions are back to being due diligence.
A working definition for the 2020s has three tests, and a property that fails any of them is expensive rather than prime.
A stricter definition
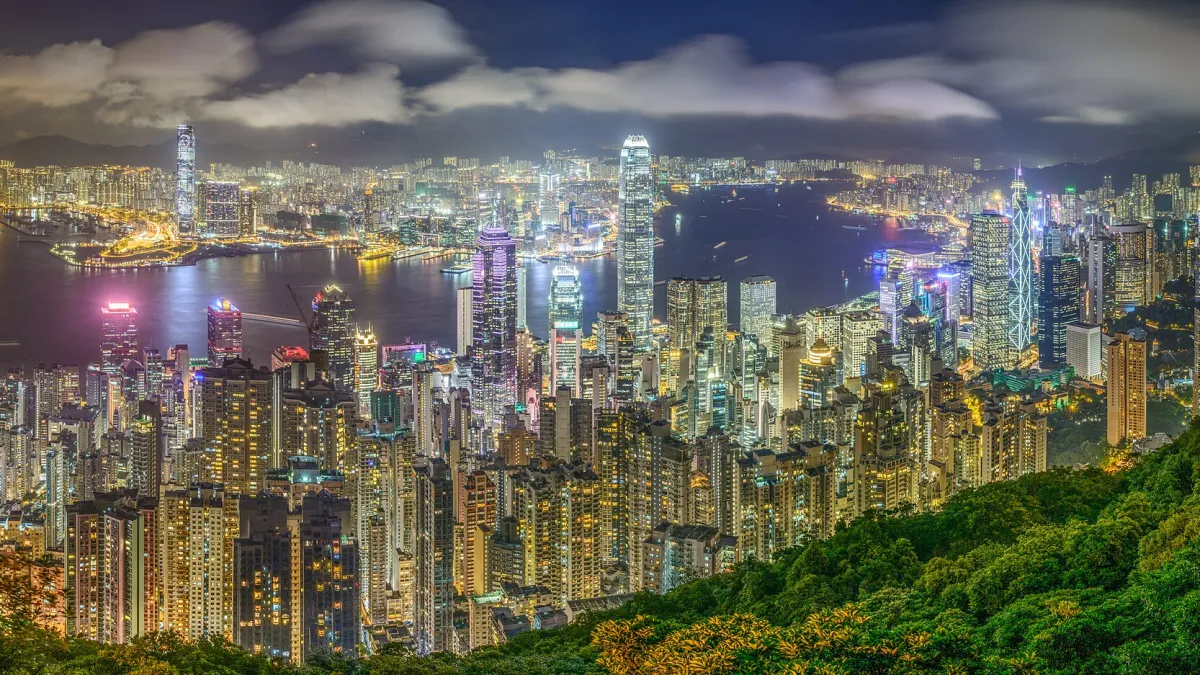
Scarcity first — but real scarcity, the kind enforced by geography, planning or both. The Peak has it; a branded tower with eight hundred units does not, whatever the brochure calls it. The test is simple: if demand doubled, could supply follow within a few years? If yes, the scarcity is manufactured.
Liquidity second. Prime property has a real market: in a normal year there are enough transactions for a seller to exit within months at a defensible price, and enough comparables for buyer and seller to argue about value from evidence. A castle that trades once a generation is not prime; it is illiquid, which is a different word with different consequences.
Third, depth of international demand. Genuine prime is wanted by more than one nation's buyers. This is not snobbery; it is insurance. A market whose buyers are all domestic is hostage to one country's tax policy, currency and politics. London's best streets, central Paris, the Palm's shoreline: each has been bought, over decades, by successive waves of different nationalities. That succession is the asset under the asset.
Why yield matters to a buyer who never lets
Trophy buyers often say they do not care about yield because they will never rent the place out. This is a category error. The yield is not about the rent; it is about the price of the option to hold. A property that would let at a real rent, after service charges, taxes and the cost of keeping it, has a floor under its value. One that yields nothing — or cannot legally be let, or sits empty in a tower of empty flats — is a pure bet on scarcity appreciation. That can be a fine bet. It should be made knowingly.
The arithmetic also disciplines comparison. Two houses at the same price, in different cities, with different carrying costs and different net yields, are different investments wearing the same price tag. In the zero-rate years, carrying costs were an afterthought. At honest rates, a house that costs real money to hold and yields nothing must appreciate just to stand still against the deposit account. Buyers do not need to love this arithmetic. They do need to run it.
Three numbers to demand
Before any prime pitch is allowed to work its charm, ask for three figures — and be suspicious of any agent who cannot produce them:
- The net running yield at today's market rent: after service charges, local property taxes and realistic maintenance, not before.
- The time-to-sell for comparable stock: how long genuinely similar properties took to find a buyer over the past two years, and at what discount to the original ask.
- The buyer mix: what share of recent purchasers in this building or street came from outside the jurisdiction.
None of these numbers requires a spreadsheet or a subscription. All three are knowable by a competent local agent, and their absence from the pitch tells you something the pitch did not intend to.
Where the label still earns its keep
The reward for this discipline is that real prime still does what it promises. Scarcity enforced by geography survives cycles; liquidity means your mistakes are recoverable; international depth means one government's bad idea is a setback rather than a death sentence. In a higher-for-longer rate environment, the premium for that combination widens rather than narrows, because the cost of holding the wrong asset has gone up.
The honest expectation for the rest of the decade is a sorting, not a crash: commodity stock marketed as prime gets repriced as what it is, while the genuinely scarce streets and shorelines go on being boringly resilient. The buyers who come out well will be the ones who treated the adjective as a claim to be audited. Three questions, asked early, do most of the auditing.