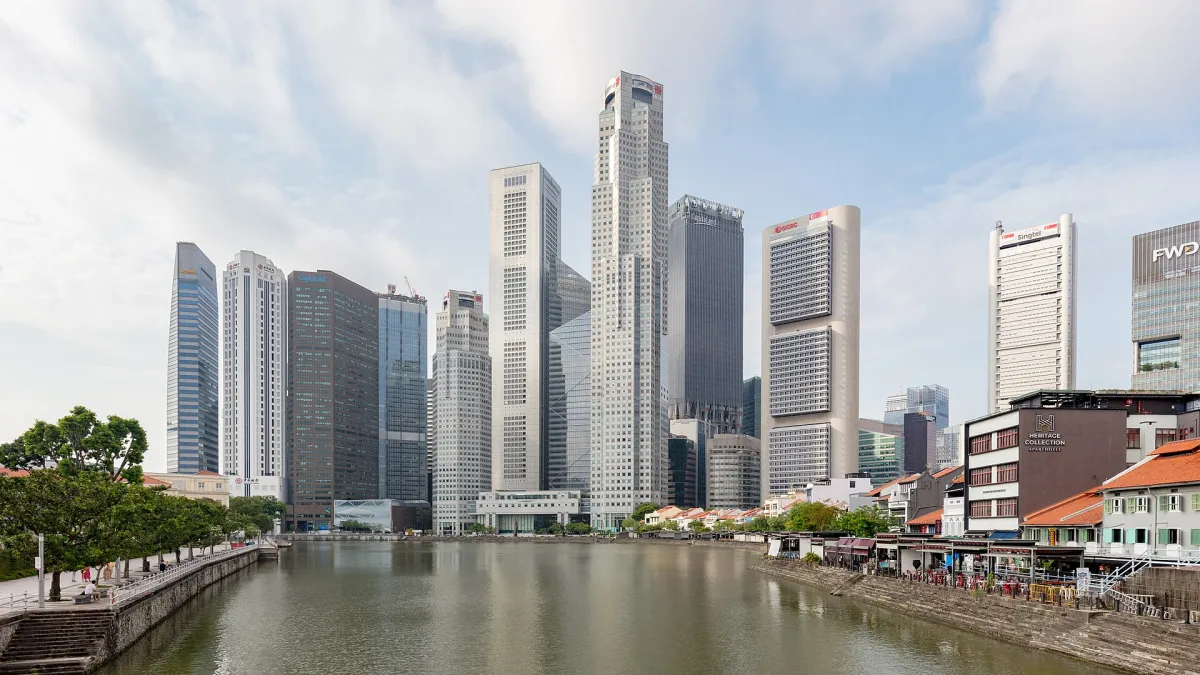
Five years ago the waiting time for a family-office tax approval in Singapore became a status symbol, the way a waiting list for a watch is. The boom that produced it has since matured into something more useful and less exciting: an industry with conditions, scrutiny and a clearer sense of who it is for.
The framework that built it
The machinery sits in two sections of Singapore's Income Tax Act, known everywhere as 13O and 13U. Both exempt specified income from designated investments when the fund is managed or advised by a Singapore-based single family office — and both now carry conditions designed to keep the benefit anchored to real activity in the city.
The 13O route, for onshore funds, requires at least S$20 million in designated investments and a minimum level of local business spending each year, tiered so that larger funds spend more, alongside at least two investment professionals. The 13U route — the enhanced tier, and the one used by larger pools including offshore structures — starts at S$50 million, demands at least three investment professionals of whom one must come from outside the family, and carries a higher local-spend floor. These parameters are public, and the direction of revision has been consistent: each update has raised the bar rather than lowered it.
Substance is the product
The phrase worth dwelling on is local spending. Singapore never sold a tax exemption; it sold a tax exemption with obligations attached. The spending and hiring conditions exist so that the family office employs people, rents offices and buys services in Singapore — which is precisely what happened. Law firms built family-office practices from nothing. Trustees, fund administrators and external asset managers multiplied. A genuine shortage of investment professionals emerged, pushing salaries for a competent Singapore-based CIO into territory that startled the families paying them.
Scrutiny tightened along the way, most sharply after a sprawling money-laundering case surfaced in 2023 and touched the sector's edges. Approvals slowed; the questions got longer. Families that experienced the process in 2021 and again recently describe two different regimes — the same scheme, but with the patience for paper-thin substance wrung out of it. That is not a flaw in the story. It is the point of it: a hub that never enforced conditions would eventually lose the credibility the conditions were meant to buy.
Who should still pick Hong Kong
The Singapore-versus-Hong-Kong framing is mostly an adviser construct — many substantial families now run both — but where a choice must be made, the honest dividers have little to do with tax rates. Hong Kong's family-office tax concession attaches no local-spending condition, which suits families whose substance is genuinely elsewhere. Hong Kong also offers what Singapore does not: the Capital Investment Entrant Scheme, which converts a qualifying investment into residency. Singapore's framework sells tax treatment; it does not sell a passport path, and families who want permanence should not confuse the two products.
The softer factors still matter. Families whose deal flow, operating businesses and language are China-facing tend to find Hong Kong's bench more natural. Families whose assets are Southeast Asian, whose children will be educated in English-medium international schools, or who simply want distance from any single large neighbour, keep choosing Singapore and sleeping well.
Five years of consequences
The boom's real legacy is institutional. Singapore now possesses a professional-services bench — lawyers who have actually drafted these structures, bankers who have left the big platforms to serve them, regulators who have seen the failure modes — that did not exist at scale in 2020. That bench compounds. Each additional family office makes the next one easier to run properly, which is the quiet advantage established hubs hold over ambitious newcomers.
The costs are real too. Office rents, school places and salaries absorbed the influx, and the city's ambivalence about visible wealth has not disappeared. A family arriving today should expect a cooler reception than the 2021 brochures implied, and a regulator more interested in the genuineness of the operation than in its press release.
What the next five years look like
Expect the conditions to keep tightening in increments — higher spending tiers, sharper definitions of qualifying investments, closer inspection of who the investment professionals actually are. Families that built real substance will barely notice; structures built to the letter of the rules rather than their spirit should expect uncomfortable reviews. Meanwhile Hong Kong and Singapore will keep converging: each has adopted pieces of the other's playbook, and the families best served will be those who stopped treating the choice as a beauty contest and started treating it as an operations decision. The brochure phase of this industry is over. The compliance phase is where the value now sits.