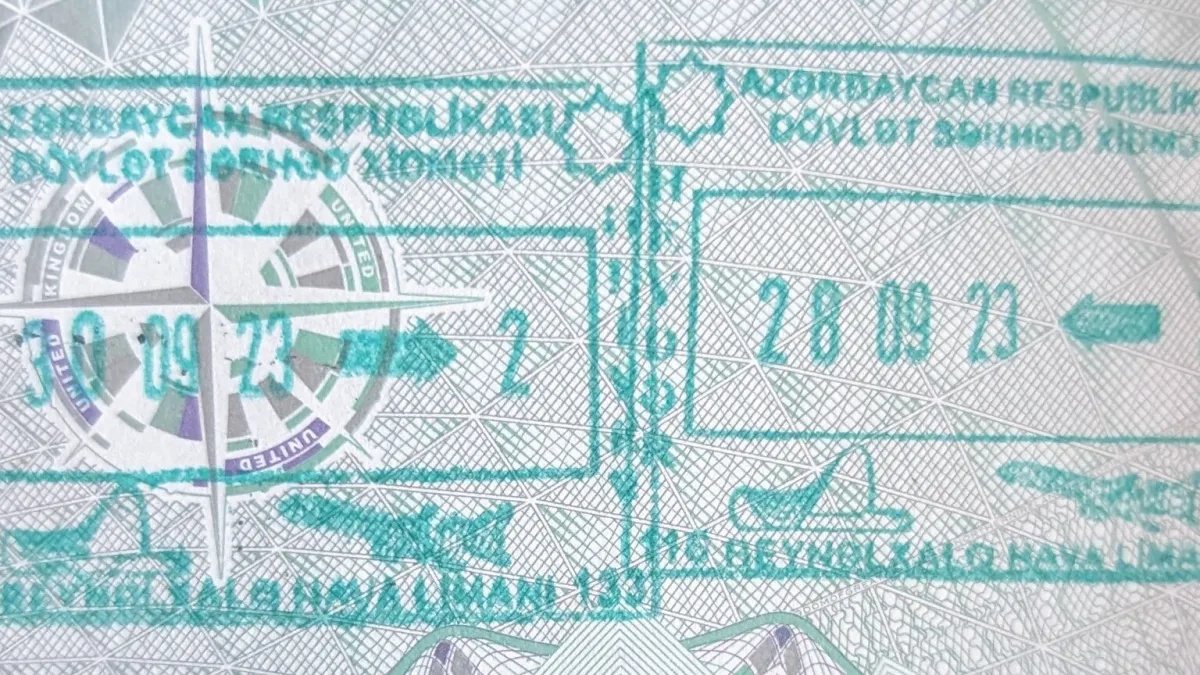
Ask a private banker where a client lives and you will get an address. Ask the client's tax adviser and you will get a spreadsheet. The spreadsheet — days, counted by jurisdiction, cross-checked against boarding passes — is the honest answer, because tax residence in the 2020s is not a fact you declare but a story you tell in days, and the authorities get to check the arithmetic.
The story matters more than ever because the consequences have grown. Residence decides which country taxes your worldwide income, and increasingly — Britain's move to residence-based inheritance tax from April 2025 being the latest example — which one taxes your estate. Getting it wrong in one direction is a surprise bill. Getting it wrong in the other is an allegation.
The shorthand that misleads
Everyone knows the 183-day rule, and almost everyone knows it wrongly. It is not an international standard; it is a common threshold with many national variations, and the variations are where people get caught. Some countries count any part of a day. Some count midnights. Some apply look-back periods across several years. Some tax you on arrival with no day-count at all if your home or your economic interests are there.
Britain's statutory residence test is the honest illustration of how complicated reality is: days interact with ties — family, accommodation, work, prior presence — so that a person can be resident on well under 183 days if the ties are dense enough. The comfortable sentence "I'm nowhere near 183 days" is, on its own, close to meaningless.
There is also the double failure. Plenty of people are resident in two countries at once under domestic rules, which is what treaties are for. And a smaller, more romantic group believes it is resident nowhere — which, in the era of automatic information exchange, is a hobby rather than a position.
What the treaties actually say
When two countries both claim you, the standard treaty tie-breakers work down a list that is really a biography. Where do you have a permanent home? If both, where are your personal and economic relations closer — the centre of vital interests? If that cannot be determined, where is your habitual abode? Then nationality, then the tax authorities negotiate over you.
Note what the list rewards: not where you registered, or where your company sits, or what you told a bank form, but where your life observably is. Centre of vital interests is the phrase that has ended more clever arrangements than any other, because it invites an inspector to ask where the business is actually run from, where the spouse sleeps, where the children go to school. Paper declarations do not survive those questions. Patterns do.
Evidence beats intention
The practical consequence is that tax residence is now an evidence discipline. Families who relocate seriously keep contemporaneous logs — travel days recorded as they happen, not reconstructed at enquiry time — and the logs are corroborated by the data trail everyone carries: card transactions, phone locations, airline records, club usage. The adviser who says "keep a diary" is not being quaint. The diary is what the story looks like when it is true.
This cuts both ways, fairly. A family that genuinely moved, and lived the move, generates the evidence without trying. A family that performed a move — a leased flat abroad, a mailbox, a spouse who "is based in Dubai now" — generates the opposite evidence with equal ease. The calendar does not lie, but it does gossip.
The family that did not move
The classic failure has a shape every practitioner recognises. The residence permit was obtained, the tax registration filed, the announcement made. But the house in the old country was kept just in case, the children finished at the same school, the dog stayed because of the flight, and one spouse commuted emotionally and then physically. Two years later, an enquiry asks where the centre of vital interests sits, and the honest answer is: exactly where it always did.
None of this argues against moving. It argues for moving completely or not at all — and for planning the year before it starts, because a tax year is a block of days that will be counted later by people who were not there. The cheapest tax advice in the industry remains the calendar: decide the story in January, live it daily, and let the spreadsheet write itself. Data sharing widens every year, and the enquiries of the coming decade will arrive better informed than the last. Families keeping the diary now will sleep through them; the rest will keep reconstructing their lives from bank statements, which is an expensive way to keep a diary.